Gerald - Cash Advance
- 4.4
- Rating
- 500.00K
- Installs
- Free
- Price
 Analysis by App-foxy
When an unexpected bill lands between paydays, I understand why a cash-advance app can look more practical than a traditional loan application. Gerald Cash Advance is built for that narrow moment: getting access to money quickly through a mobile finance app rather than going through a conventional credit process. I found the experience straightforward enough for short-term needs, but it works best when treated as a carefully managed bridge, not as extra income.
Gerald Technologies, Inc. develops the app, which is free to install and carries an Everyone age rating. It has grown beyond a small experiment, with more than half a million installs and a 4.4 average from roughly ten thousand ratings. Those figures suggest that plenty of people find the basic idea useful, although popularity should not replace checking the terms and repayment details that apply to your own account.
Using Gerald Cash Advance in a real everyday situation
My preferred way to use a service like this is to begin with a very specific gap. Imagine a utility payment is due today, while your normal deposit arrives in a few days. Instead of opening the app and requesting the largest amount available, I would first write down the exact bill, the expected deposit date, and the amount that must remain available for food, transport, and other essentials. That small calculation changes the app from an impulse button into a controlled tool.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk



The usual workflow is simple in concept. I open the app, review the available cash-advance option, check the amount and the expected repayment conditions, and only then decide whether to continue. The important part is not the tapping; it is confirming that the advance fits the timing of my next income. A fast request can solve one problem while creating another if the repayment arrives before the money needed for basic expenses.
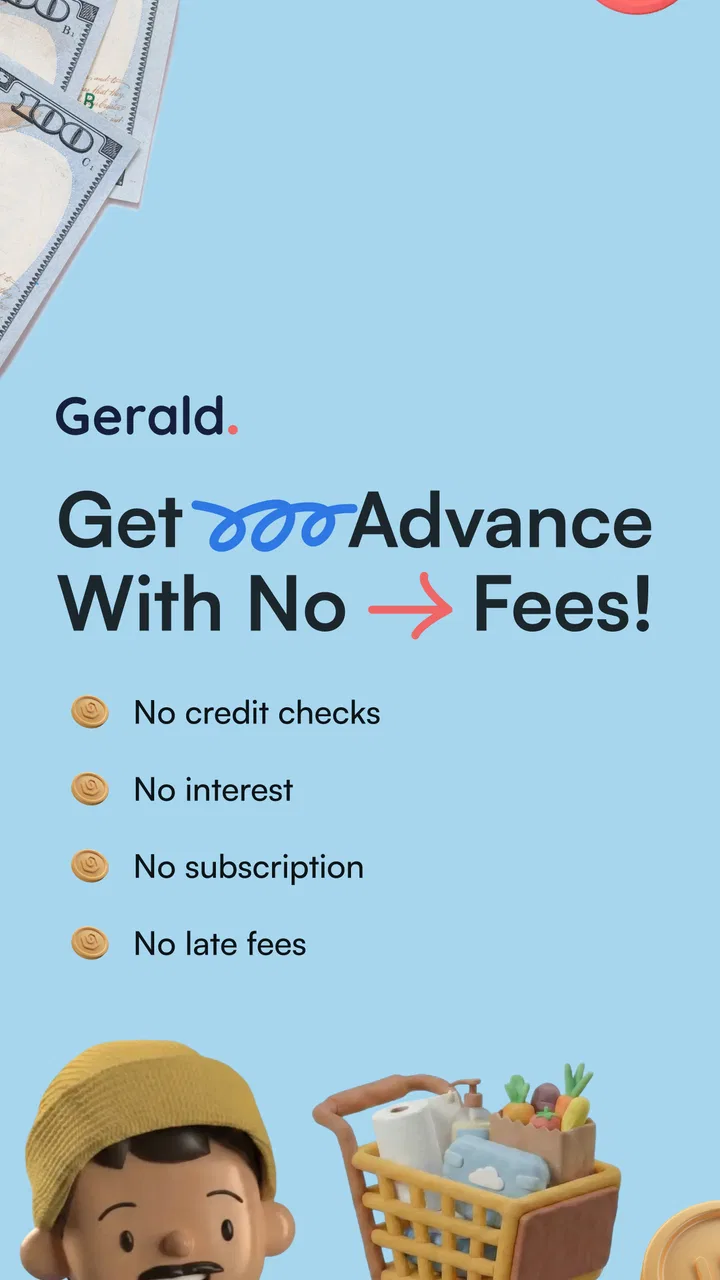
The service presents itself around access without a credit check and without interest. That can make it more approachable than a credit card cash withdrawal or a conventional personal-loan application. Still, “no interest” should not be read as “no possible cost or responsibility.” I would inspect every screen for any optional service, expedited delivery charge, membership condition, or repayment wording before accepting anything. The exact total that matters to me is what leaves my account and when it leaves.
One useful habit is to take a momentary screenshot or note of the confirmation details for my own records, provided the screen contains no sensitive information I should store carelessly. I would record the advance amount, the expected repayment date, and any visible fee. That makes it easier to compare the transaction with my bank activity later and prevents the common mistake of forgetting that a small advance is scheduled to come out.
Gerald is most appealing when the need is temporary and clearly defined. A modest gap caused by a delayed paycheck or an urgent household expense is a more sensible use than recurring rent shortfalls, ongoing debt payments, or everyday spending that already exceeds income. If I needed money every week, I would see that as a budgeting warning and look for a longer-term solution instead of repeatedly extending the same pattern.
What I would check before requesting money
I would first confirm that the account receiving or repaying the advance is the account I actually monitor. A forgotten old bank connection can create avoidable confusion. I would also check whether my next deposit is large and stable enough to cover the repayment while leaving a realistic cushion. Predictable timing matters more than the maximum amount shown in the app.
I would then read the final review screen slowly. The most important questions are practical: how much will I receive, how much will be repaid, on what date, and what happens if that date no longer matches my cash flow? Even when an app is designed to be friendly, a finance transaction deserves the same attention as a bill or bank transfer.
Another good rule is to request only the amount tied to the immediate problem. If a bill is short by a small amount, taking extra cash simply because it is available increases the repayment burden without improving the original situation. This is one of the clearest differences between responsible use and treating an advance as disposable spending money.
Settings and account habits worth checking
Instead of assuming the default setup suits me, I would review the account and notification areas after signing in. The useful questions are whether contact information is current, whether the linked payment account is still correct, and whether alerts are enabled for important transaction events. I would not disable reminders just to reduce notifications; for a short-term advance, a repayment reminder is more valuable than a quieter inbox.
I would also review the app after changing banks, replacing a phone, or updating my main email address. Financial apps depend heavily on current account information, and a connection that was correct months ago may no longer reflect the account where my income arrives. Keeping those details tidy is a less visible but more important part of using a cash-advance service safely.
Privacy deserves attention too. I would grant only the access needed for the service to function and would avoid entering information into unofficial pages or messages that imitate the app. Gerald Cash Advance is a finance product, so I would treat every request for personal or banking information cautiously and open the app directly rather than relying on a suspicious notification.
There is also a useful separation between notification settings and financial planning. I might allow alerts for approval, transfer, or repayment activity, while silencing promotional messages if the app offers that choice. The goal is to make the alerts that protect me noticeable without letting frequent marketing encourage unnecessary borrowing.
Faster patterns that still keep control
Experienced use is less about rushing and more about repeating a safe sequence. I would keep a small note in my budgeting app called “advance check” with four items: reason for the request, amount needed, next income date, and money left after repayment. Each time I consider using Gerald, I can fill in those fields before opening the request screen. It takes less time than repairing an overdrawn account later.
For a one-off emergency, I would complete the request during a calm moment rather than while standing at a checkout. A checkout problem creates pressure, and pressure makes optional extras or an unnecessarily large request easier to accept. Preparing the amount in advance also reduces the chance of mistyping or overlooking the final repayment information.
I would use the app as a gap-filler, not as a replacement for a spending plan. If the same subscription, grocery trip, or transport cost repeatedly triggers an advance, I would move that expense into a weekly budget and address the underlying shortfall. The faster pattern is not requesting money more often; it is learning which expenses repeatedly cause the request and dealing with them directly.
It is also worth checking the bank account after the transaction rather than assuming everything completed exactly as expected. I would compare the received amount with the confirmation, then check again when repayment occurs. This two-check routine catches mismatches early and gives me a clearer record if I need help from support.
Compared with a credit card, Gerald may be preferable for someone who wants to avoid revolving interest and already knows exactly when the shortfall will end. A credit card can be more flexible for purchases and may offer protections or rewards, but carrying a balance can become expensive. Compared with asking a bank for a personal loan, the app is more convenient for a small, urgent gap, while a bank loan may be more appropriate for a larger planned expense with a longer repayment schedule.
Compared with borrowing from a friend or family member, an app can feel less awkward and more immediate, but it does not remove the need to plan. A personal loan from someone you trust may offer more flexibility, whereas a digital service gives the transaction a formal structure. The better choice depends on urgency, amount, repayment certainty, and the relationship involved.
Where the convenience reaches its limits
The phrase “no credit check” is helpful for people who may not qualify for conventional credit, but it should not be confused with guaranteed approval or unlimited access. Financial services still need to evaluate whether a transaction can be offered, and availability can depend on account circumstances. I would never build a rent or medical plan around money I have not yet been approved to receive.
The absence of interest also does not make repeated advances harmless. If each repayment leaves me short again, the cycle can become a form of dependence even when each individual transaction appears manageable. The real cost may be the loss of flexibility on the next payday. That is why I prefer to judge the app by the month after using it, not only by how quickly it solves today’s problem.
Another limitation is that mobile convenience can hide the seriousness of the transaction. A few taps feel lighter than a visit to a lender, but the repayment still affects the same household budget. I would avoid using the app during emotional shopping, gambling, or any situation where the reason for borrowing is not clear enough to explain in one sentence.
People who need a larger amount, a longer repayment period, or a predictable installment schedule may be better served by a traditional loan, a credit union, a negotiated payment plan, or nonprofit financial counseling. Someone with irregular income should be especially careful, because a repayment tied to an uncertain deposit can create a second emergency. Gerald is not a substitute for an emergency fund, though it may help while building one if used sparingly.
Technical friction can matter as well. Keeping the app updated is sensible, and the current version is 69.0.9 for devices running Android 7.0 or later. If an older phone cannot run that environment reliably, I would not use a borrowed or insecure device for financial access. I would also avoid public Wi-Fi when entering sensitive information and make sure the phone itself is protected with a passcode.
Support is another reason to keep records. If a transfer or repayment does not look right, I would save the transaction details, note the time of the issue, and contact the developer’s official support route from inside the app or its legitimate store presence. I would not send banking credentials through an unsolicited message claiming to represent Gerald Technologies, Inc.
My verdict after looking at the complete workflow
Gerald Cash Advance makes the most sense for a person facing a small, temporary cash gap who can identify the repayment source with confidence. I like the direct mobile approach and the appeal of avoiding a credit check and interest-based borrowing. The free entry point also makes it easy to explore, although I would still read the transaction terms rather than assuming every use is costless.
Its strongest quality is not that it makes money appear instantly; it is that it can provide a structured alternative to more expensive forms of short-term borrowing when the timing is clear. The best users will set a limit before opening the app, confirm the repayment impact, keep alerts active, and review their bank account afterward. Those habits turn convenience into control.
I would skip it if my income is already committed, if I am trying to cover a recurring deficit, or if I cannot say exactly how repayment will fit into the next budget. In those situations, a conversation with a bill provider, a credit counselor, a credit union, or a trusted person may be safer than another advance. The application cannot fix an income-and-expense mismatch by itself.
For eligible users on Android, the app is free and available to an Everyone audience, and its 4.4 average across around ten thousand ratings shows that many users respond positively to the concept. I would interpret that as encouragement to investigate, not as a promise that every person will receive the same result. My recommendation is cautious but positive: use Gerald for a defined short-term need, keep the amount tight, and make repayment planning the first step rather than an afterthought.
FAQs for Gerald - Cash Advance
01What is Gerald - Cash Advance, and how does it work?
Gerald is a financial app designed to provide eligible users with access to an interest-free cash advance, often referred to as a “Balance.” After creating an account and completing the required identity and eligibility checks, you may be able to request money and receive it through the available delivery options. Approval, limits, and processing times can vary by user and transaction.
02Does Gerald charge interest, fees, or a subscription for cash advances?
Gerald promotes its cash advance service as interest-free, which means users generally do not pay traditional interest on an advance. However, you should carefully review the current terms before accepting money because optional expedited delivery, membership features, late-payment policies, or other services may involve charges. Pricing and availability can change, so always confirm the final cost inside the app.
03Who can use Gerald - Cash Advance?
Access is not guaranteed for every applicant. Gerald may require users to be at least 18 years old, live in a supported location, provide valid personal information, and connect an eligible bank account or card. The app may also evaluate account activity, income patterns, repayment history, and other factors when determining eligibility. Requirements can change and should be checked during registration.
04How quickly can I receive money from Gerald?
The delivery time depends on the transfer method selected, your bank or card provider, account verification, and whether the request is processed during business hours. Some users may receive funds quickly, while standard transfers can take longer. Before confirming an advance, review the estimated arrival date and any optional instant-delivery charge shown in the app.
05What should I know about repayment before taking a Gerald advance?
Before requesting money, make sure you understand the repayment date, amount, and account that Gerald will use to collect the balance. An advance is not free money and should only be taken if you expect to have sufficient funds when repayment is due. Failed or delayed repayment could affect access to future advances and may result in additional consequences under the current agreement.
Pros
- Simple application process with minimal paperwork
- Fast eligibility checks can save time in emergencies
- Clear repayment schedules help users plan ahead
- Useful for borrowers with limited traditional credit options
- Mobile access makes managing an advance convenient
Cons
- Cash advances may carry high fees or interest costs
- Late payments can lead to additional charges
- Approval and loan terms vary by applicant
- Availability may depend on location and eligibility
- Frequent borrowing can create a cycle of debt

Gerald - Cash Advance
Gallery